iro INVESTMENT

Strategies / midori

緑 midori US equities Research live

Great American businesses, held patiently.

A concentrated, long-only model portfolio of 12 to 20 quality US companies, selected through fundamental research with a five-to-ten-year investment horizon.

A survey-style topographic landscape in shades of green
12–20
companies in the model portfolio
5–10
years, the investment horizon
381
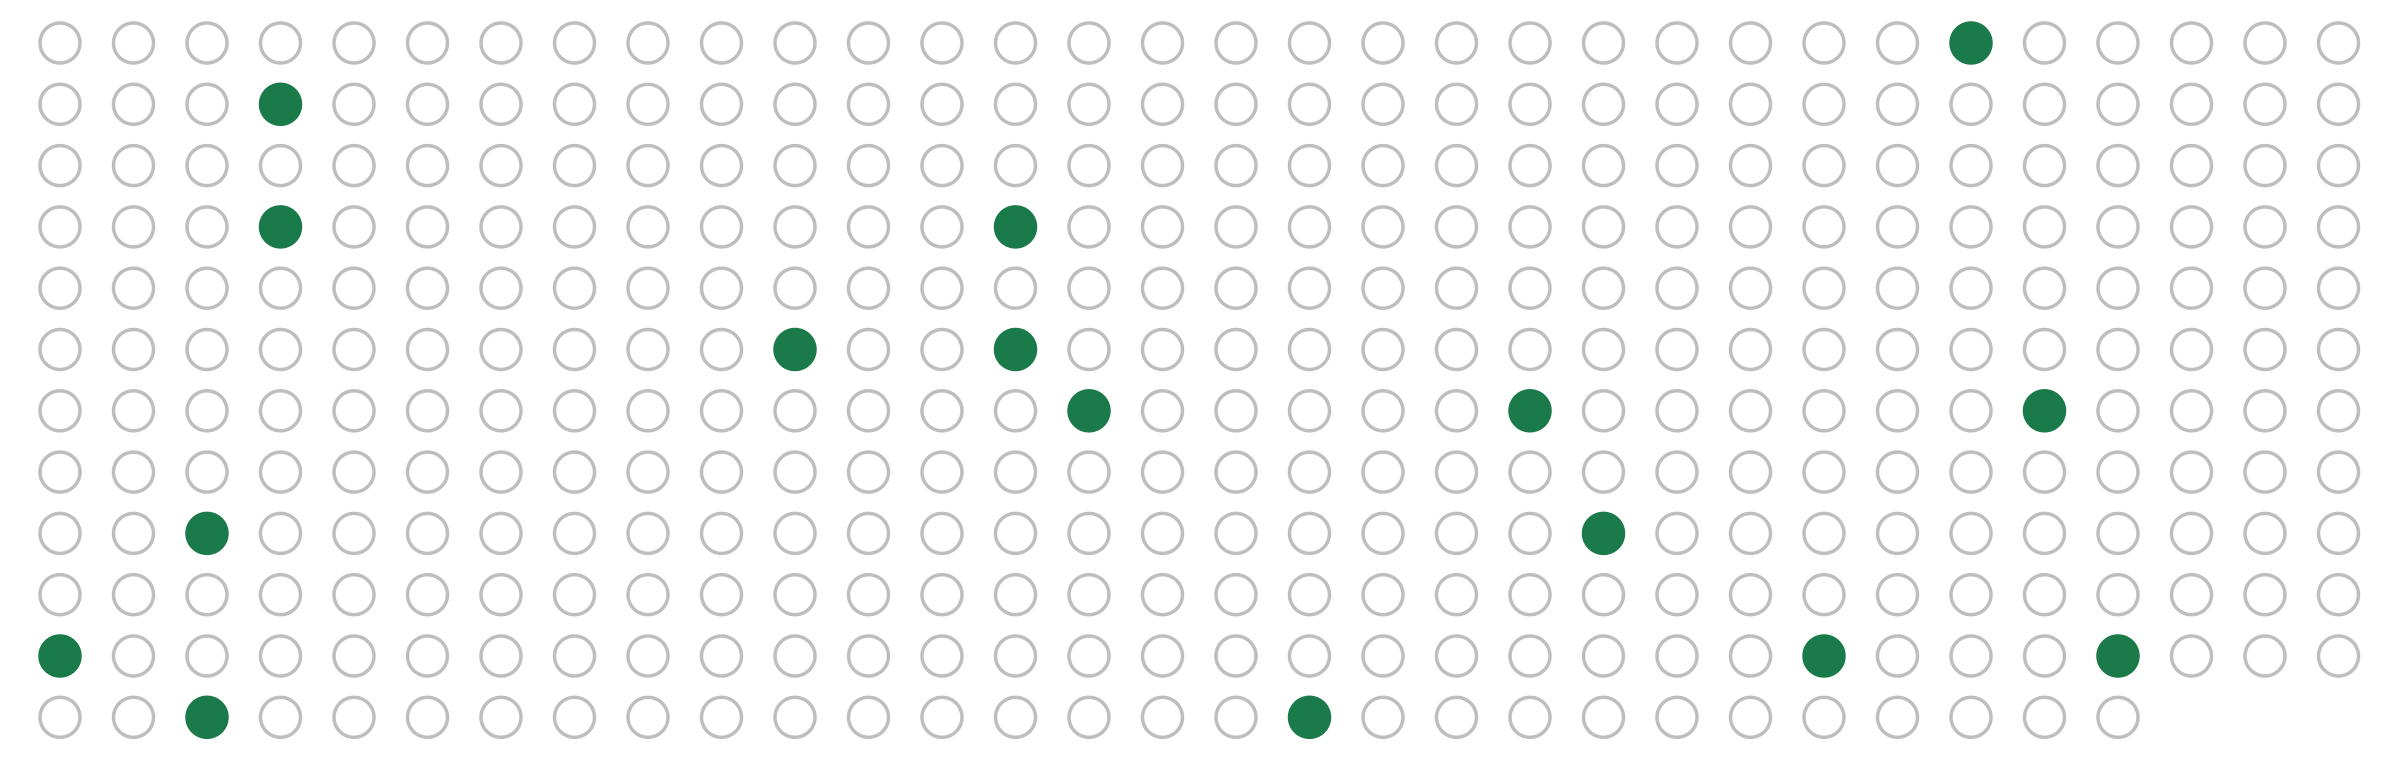
companies pass the mandate
0%
leverage, shorts or derivatives

Selection

From 381, a handful.

A grid of 381 circles with 16 highlighted in green illustrates concentrated selection rather than current holdings

The mandate

What qualifies, and what we exclude.

What qualifies

Common shares listed on the NYSE, NASDAQ and NYSE American, in businesses that can keep a durable advantage for five to ten years or more.

There is no size floor. Companies under $1 billion must show adequate liquidity and disclosure. Retailers are judged one by one, on evidence of a real mechanism such as purchasing scale or franchise royalties, never on management's own claims.

What we exclude

  • Banks, lenders and insurance underwriters
  • Airlines and mass-market carmakers
  • Mining, oil and gas, and refining businesses
  • Manufacturers of steel, basic chemicals and paper
  • Tobacco
  • Audit concerns, opaque structures and serial fundraisers

Research time

Where we look hardest.

50%

Under-covered companies

Mostly $1 billion to $50 billion in value, where fewer analysts are looking.

30%

Compounders

Proven, high-return businesses, bought only at a sensible price.

20%

Event-driven

Quality businesses mispriced by a one-off event.

Process

How a report is made.

i.

Screen

The mandate narrows the US market to 381 eligible companies.

ii.

Gather

Company filings, earnings calls and ten years of financial results form the evidence base.

iii.

Analyse

We examine competitive advantage, management's allocation of capital and the risks that could erode future earnings.

iv.

Value

We value owner cash flow after stock-based compensation, using explicit assumptions for share count and the cost of equity.

v.

Challenge

An independent review tests the figures, valuation assumptions and counterarguments before the report is finalised.

Each report includes a fair value estimate and a rating. We assign Buy when the expected return beats the cost of equity by 2 points and Sell when it falls 2 points short. A return between those thresholds receives a Hold rating.

Risk rules

Risk limits, set in advance.

8%

Largest starting position. Reviewed if it grows past 12%.

30%

Most in any one sector.

5 days

Positions are sized for an exit within five trading days at no more than 5% of daily volume.

−15%

Drawdown that triggers a full review. At −25%, no new positions.

Companies with net debt above 2.5× EBITDA get a balance-sheet review. VTI, the US total market, is our primary benchmark. SPY provides a second comparison.

Research

Latest notes

All research →
31 Oct 2026 · Initiation Hold

Automatic Data Processing (ADP)

A wide moat, with client retention steady at about 92% for six years. But recent margin gains lean on interest earned on client funds, not the core business. Fairly priced.

Fair value
$278
Price, 30 Oct 2026
$293.84
Coming · Initiation In review

Intuit (INTU)

Initiation in progress.

Model portfolio

A concentrated model portfolio built from our published research, with performance measured against VTI, the US total market benchmark.

NEXT STRATEGY
aka →
China equities · In development
赤
NEXT STRATEGY
kuro →
Private equity · Planned
黒